
CBN Slashes Rate to 23%: What Changes for Borrowers, Businesses and the Economy?
For years, expensive credit has been one of the biggest complaints from Nigerian businesses and consumers.
Now, the Central Bank of Nigeria has made a move that could change the cost of borrowing , although the impact may not be felt immediately.
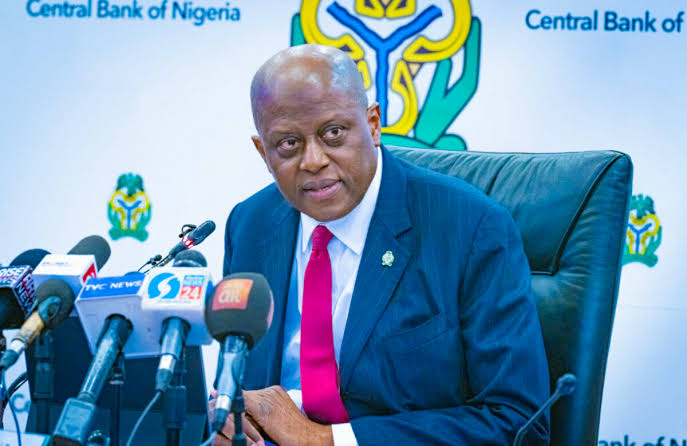
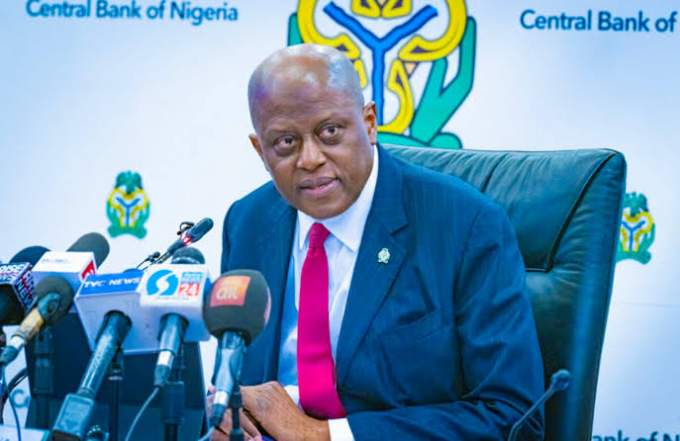
The CBN’s Monetary Policy Committee on Tuesday reduced the Monetary Policy Rate from 26.5 per cent to 23 per cent, cutting 350 basis points at its 307th meeting in Abuja.
The decision marks a major shift after the committee had kept the benchmark rate unchanged at 26.5 per cent at its previous two meetings.
CBN Governor Olayemi Cardoso said the committee decided to “reset” the MPR and adjust the policy corridor to improve the way monetary policy affects the wider economy.
The new asymmetric corridor was set at +50/-300 basis points around the MPR, compared with the previous +50/-450 basis points.
But while the headline figure suggests cheaper money, the real question is whether ordinary businesses and consumers will actually see a meaningful reduction in lending rates.
Why the CBN cut the rate
The decision came against the backdrop of easing inflation and improved conditions in the foreign exchange market.
Nigeria’s headline inflation stood at 15.39 per cent in August, down from 15.43 per cent in July, according to the National Bureau of Statistics.
The continued moderation in inflation has created more room for the CBN to ease some of the pressure imposed by its earlier tight monetary policy.
The latest decision is the second reduction in the MPR this year and the largest single cut in the current policy cycle. Some analysts have described it as a significant change in the direction of monetary policy.
For businesses, the attraction is straightforward: if banks eventually reduce their lending rates, companies could have access to cheaper funds for expansion, working capital, equipment and new investments.
Dr Muda Yusuf, Chief Executive Officer of the Centre for the Promotion of Private Enterprise, said the decision represents a significant shift away from the prolonged restrictive monetary policy environment.
He argued that the lower policy rate could help reduce the cost of capital and improve business cash flow, particularly in sectors such as manufacturing, agriculture, construction and logistics.
But Yusuf also stressed that the benefit would depend largely on how quickly commercial banks pass the reduction on to borrowers.
Cheaper loans may not come immediately
This is where the debate begins.
Economist Dr Marcel Okeke questioned the size of the reduction, describing the 350-basis-point move as unusually large.
He also cautioned against assuming that a lower MPR would automatically translate into cheaper loans.
According to Okeke, banks consider several factors when deciding how much to charge borrowers, meaning the reduction in the CBN’s benchmark rate does not by itself determine the final interest rate paid by customers.
He also argued that Nigeria’s broader business environment must improve if cheaper monetary conditions are to translate into stronger economic activity.
In other words, reducing the price of money may help, but it does not remove other costs and risks faced by businesses.
The CRR remains a major factor
Another important part of the CBN’s decision is what it did not change.
The committee retained the Cash Reserve Ratio for commercial banks at 45 per cent and kept the requirement for merchant banks at 16 per cent. The CRR on non-Treasury Single Account public-sector deposits also remained at 75 per cent.
That means banks are still required to keep substantial portions of certain deposits as reserves rather than lending them out.
This could limit how quickly the rate cut feeds into the wider economy.
Former Securities and Exchange Commission Director-General Suleyman A. Ndanusa said the decision could eventually lower borrowing costs, reduce pressure from government debt servicing and give businesses and households more financial breathing room.
However, he noted that the continued high CRR requirements could prevent cheaper credit from reaching borrowers as quickly as the headline rate suggests.
What it could mean for Nigerians
If banks respond by reducing lending rates, businesses may find it easier to finance expansion and working capital.
Consumers could also benefit if lending costs fall on products such as personal loans and mortgages, although the speed and extent of any reduction will depend on individual banks and market conditions.
For investors, the lower MPR could also affect the relative attractiveness of fixed-income assets and equities as market participants adjust to a new interest-rate environment. Analysts have already pointed to the possibility of increased demand for equities as investors reconsider where to place their money.
But cheaper credit is not guaranteed overnight.
The CBN has lowered its benchmark rate, yet banks still face reserve requirements and other funding costs. Businesses also continue to deal with issues such as infrastructure gaps, exchange-rate risks and other operating expenses.
That leaves the biggest question unanswered: will the 23 per cent MPR translate into noticeably cheaper loans on the streets of Nigeria?
The answer will depend less on the announcement itself and more on what banks do with it in the months ahead.


Leave a comment